
- ✓A homeowner can qualify for two mortgages and still prefer not to use most of their cash or carry an existing property while it sells.
- ✓A traditional sale, sale contingency, HELOC, bridge loan, or acquisition program can solve different timing, equity, and cash-reserve problems.
- ✓Cash to Win describes seller and buyer options that can create purchase proceeds before a prior home sells or support a cash offer on the next home.
- ✓Program fees, per-diem charges, closing expenses, repairs, expected resale value, and holdbacks can change the final proceeds.
- ✓Start with the homeowner's desired outcome, current mortgage, available equity, cash reserves, and timing before recommending a structure.
I recently worked with a buyer who had an $800,000 home, substantial equity, a good income, and enough money in the bank for a down payment on his next property.
He qualified to carry both mortgages.
You would think this would be a straightforward transaction.
Except he and his wife had one concern. They didn't want to use nearly all their available cash for the down payment and then sit around waiting for their existing home to sell.
And I understood their concern.
The house might sell in 30 days. It might take 90. Nobody knows exactly how long a property will sit on the market.
They weren't worried about qualifying for the mortgage. They were worried about what their financial situation would look like while carrying two properties.
So we started exploring ways to access the equity in their existing home.
A HELOC was one possibility. A bridge loan was another. We also discussed a program called Cash to Win, which approaches the buy-before-you-sell problem differently.
That conversation reinforced something I've been thinking about for a while.
Sometimes the biggest obstacle to getting a real estate transaction completed has nothing to do with whether the buyer qualifies for a mortgage.
It's the order in which everything needs to happen.
And when you understand how to solve that problem, you have an entirely different conversation with your clients.
Your Seller Is Ready to Move. Their Equity Is Still Sitting in the House.
Think about the homeowners you're working with in Franklin, Brentwood, Spring Hill, and the surrounding Middle Tennessee communities.
You have people who have lived in their homes for 15 or 20 years. They've built substantial equity, but they don't necessarily have hundreds of thousands of dollars sitting in the bank.
Then you have move-up buyers who need the proceeds from their current property to purchase something larger.
And you have homeowners downsizing from a 4,000-square-foot house into something smaller and easier to maintain. They would love to find the next property, move once, and sell their existing home afterward.
Different situations, but the underlying problem is similar.
Their money is tied up in a property they haven't sold.
Traditionally, you have several ways to approach this. Sell first and purchase afterward. Make an offer contingent on selling the existing property. Qualify the buyer to carry both mortgages. Or borrow against the equity in the current home.
Each approach works under the right circumstances. Each also creates potential complications.
A contingent offer might be less attractive to the seller of the next property. Carrying two mortgages creates additional monthly expenses. A HELOC adds another payment. Selling first might mean temporary housing and moving twice.
Sometimes the homeowner decides to wait because none of those options sounds particularly appealing.
That's where understanding alternative acquisition programs becomes useful.
What If Your Client Had Access to Their Equity Before Selling?
I recently sat down with Brian, the founder of Cash to Win, to discuss how his company handles these transactions.
Cash to Win is a real estate acquisition company. One of its programs allows homeowners to access a portion of their existing property's value before the property sells to its eventual buyer.
The company acquires the property and advances funds based on its value. The homeowner uses those proceeds toward the next purchase.
Meanwhile, the original property is marketed for resale through a real estate agent.
When the property sells, the remaining proceeds are distributed according to the agreement, after applicable costs.
Brian explained that the company typically advances approximately 70% of the property's value, although the actual amount depends on the transaction.
Let's use a simple example.
Your client owns an $800,000 property with a $250,000 mortgage.
At a 70% advance, the initial acquisition amount would be $560,000. After paying off the existing $250,000 mortgage, approximately $310,000 would be available before program fees, closing expenses, and other adjustments.
The homeowner now has funds available for the next purchase.
The original property continues through the resale process.
Of course, the company charges acquisition and carrying fees. The eventual resale price also affects the homeowner's final proceeds.
This isn't free money. The homeowner isn't guaranteed every dollar of the property's estimated value.
But the structure addresses a problem traditional mortgage financing doesn't always solve conveniently.
It separates the timing of the next purchase from the timing of the final sale.
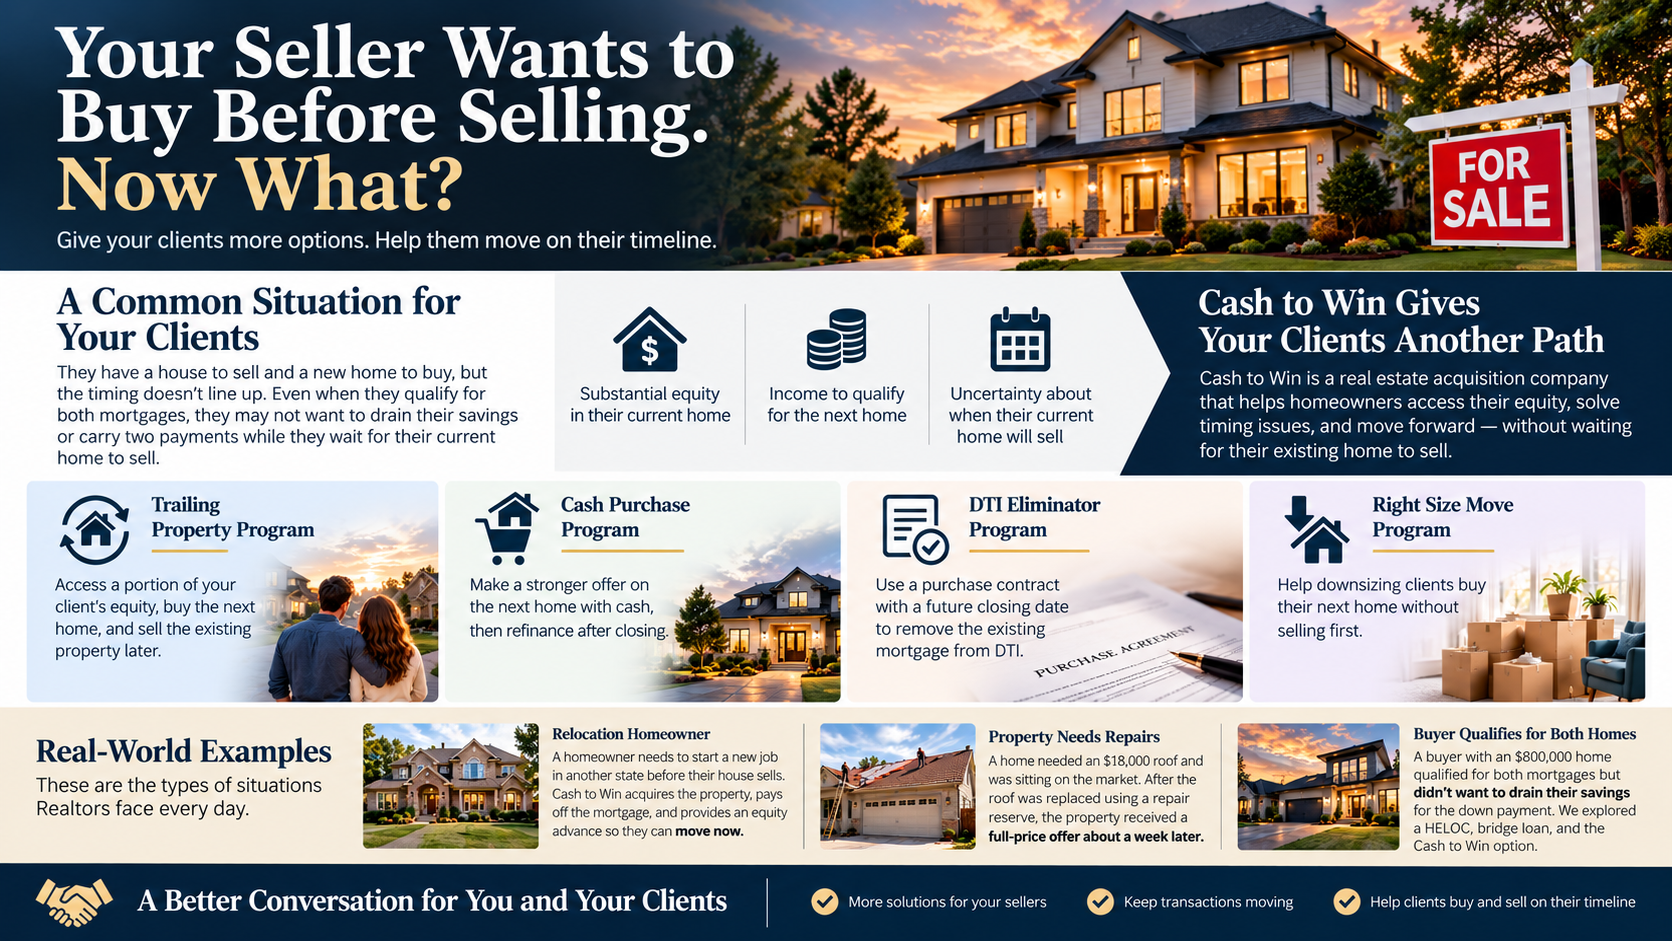
Buy-before-selling options and real-world Cash to Win examples for Realtor clients
Why This Changes Your Listing Presentation
Picture your next listing appointment.
You walk through the property. You discuss pricing, comparable sales, photography, marketing, and your strategy for getting the house sold.
Your competitors are discussing many of the same things.
Now consider asking a different question.
"What happens if we find your next house before this one sells?"
Suddenly, you're discussing something beyond the listing.
Perhaps the homeowner is relocating for work and has a deadline. Perhaps they're downsizing and don't want to move into temporary housing. Perhaps they're purchasing new construction and the builder expects them to close before their existing property sells.
Or perhaps they've already found the next house but haven't listed their current property because they don't know how to coordinate everything.
Instead of discussing only how you'll sell their house, you're discussing how to accomplish their entire move.
You might determine that a traditional sale is the appropriate approach. You might find that a HELOC solves the problem.
Or an acquisition program might provide the flexibility the homeowner needs.
The value of the conversation doesn't depend on using a particular program.
You've identified the problem and started working through the available solutions.
What About the Listing That's Been Sitting for Four Months?
Here's another situation worth considering.
You have a listing that's been on the market for 120 days. The seller originally wanted $750,000. You've had showings, some interest, and perhaps a couple of offers, but nothing has come together.
Meanwhile, the seller has already relocated.
They're carrying expenses on two properties, and their patience is wearing thin.
You know the property will sell at the right price. The question is how much longer the homeowner wants to wait.
This is another situation Brian and I discussed.
Cash to Win potentially acquires the existing property, pays off the mortgage, and provides the homeowner with an equity advance.
The property remains on the market with a real estate agent.
The homeowner moves forward without continuing to carry the original mortgage payment. The program's carrying charges and other expenses still affect the final proceeds.
And that's an important distinction.
You're not eliminating the cost of waiting. You're changing how the transaction is financed and when the homeowner receives their money.
For some sellers, the additional expense won't make sense. They have plenty of time and sufficient cash reserves.
For others, having access to their equity today is worth more than waiting another three months for a traditional closing.
Your job is to help them understand the difference.
One thing I appreciated during my conversation with Brian was his explanation that his company regularly encourages homeowners to sell traditionally when their circumstances don't warrant the additional expense.
I agree with that approach.
A financing solution should solve a real problem. Otherwise, you're adding cost and complexity to a transaction that doesn't need either.
What About the House That Needs $20,000 in Repairs?
This part of our conversation caught my attention because I see how often property condition affects financing and negotiations.
Brian described a property that needed an $18,000 roof replacement.
The house had been sitting on the market. Buyers liked the property, but the roof kept becoming an obstacle.
According to Brian, offers were coming in substantially below asking price.
His company arranged to replace the roof. The property was temporarily removed from the market, the work was completed, and the house was relisted.
He reported receiving a full-price offer approximately one week later.
The repair cost $18,000. The difference between the earlier offers and the eventual sale price was approximately $60,000.
Now, that's a company-reported example, and other factors affected the transaction. But the underlying problem is familiar.
Sometimes a seller has substantial equity but doesn't have the available cash to prepare the property properly.
Brian explained that Cash to Win sometimes establishes a repair reserve from the initial acquisition proceeds.
For example, a $350,000 acquisition amount might include a $20,000 reserve for necessary work.
The company coordinates payment to contractors and prepares the property for resale. The actual structure depends on the property and the company's approval.
More Closings. Fewer Financing Surprises.
Tired of deals dying because your buyer's lender dropped the ball? Keith is the mortgage partner listing agents call when they need deals protected, difficult files approved, and buyers who show up pre-qualified.
For Realtors working with inherited properties, older homes, or sellers who have deferred maintenance, this creates another potential conversation.
Instead of automatically listing the property in its current condition or asking the homeowner to fund repairs, you evaluate whether the equity supports another approach.
You still need to determine whether the expected improvement in resale value justifies the work.
Spending $20,000 doesn't automatically increase a property's value by $40,000.
But understanding the available financing and acquisition options gives you more flexibility when advising the homeowner.
What If Your Buyer Made a Cash Offer on Their Next Home?
We also discussed the purchase side of the transaction.
What if your buyer purchased their next home with cash, even though they ultimately intended to finance the property with a mortgage?
Cash to Win has a separate purchase program.
The company acquires the property with cash and subsequently sells it to the buyer.
Brian described a purchase fee of approximately 0.5% of the acquisition price, plus applicable transaction expenses.
On a $500,000 purchase, the stated fee would be $2,500 before those additional costs.
The reason to consider the program is the potential negotiating advantage of a cash transaction.
Brian shared an example involving a builder offering financing incentives on a new home.
The builder's advertised package included a reduced mortgage rate.
But when Cash to Win asked what the builder would accept for a cash purchase, the negotiated price was substantially lower.
The buyer ultimately financed the home at a higher interest rate but with a smaller mortgage balance.
According to Brian, the resulting payment was lower than the payment associated with the builder's advertised financing package.
That's an interesting example because buyers frequently focus on the advertised interest rate without considering the entire transaction.
I've spent years explaining this distinction to buyers.
A lower advertised interest rate doesn't automatically mean a better financial outcome.
Sometimes reducing the purchase price produces a more favorable result. Sometimes the builder's incentive package is the stronger option.
You need to evaluate the purchase price, financing incentives, closing costs, and monthly payment together.
And you need to account for the additional expenses associated with the cash acquisition.
Cash offers don't automatically produce substantial discounts. The numbers have to support the strategy.
Don't Overlook the Homeowner Who Already Qualifies for Both Houses
Let's return to my $800,000 buyer.
He qualified for both mortgages. He had sufficient income and a down payment available.
What he didn't want was to exhaust his reserves.
That's a completely different problem from a borrower who doesn't qualify because of debt-to-income ratios.
For this buyer, I wanted to evaluate the cost of using existing cash, opening a HELOC, obtaining bridge financing, or using an acquisition program.
The comparison needs to account for the total transaction cost, monthly cash flow, remaining reserves, and expected time required to sell the existing property.
A HELOC might be the least expensive solution.
A bridge loan might provide the appropriate structure.
Or the homeowner might prefer an acquisition program because it removes the existing property from their immediate ownership and financing responsibilities.
The point is to understand what the client is trying to accomplish before recommending a particular product.
If you send me a buyer in this situation, I'm not going to start by asking which loan program they want.
I'm going to ask how much cash they want available after closing, what they owe on their current property, and what happens if that property takes six months to sell.
Those answers tell us which options deserve consideration.
And this is something I wish more Realtors understood.
A buyer who qualifies for two mortgages isn't necessarily comfortable carrying two mortgages.
Qualification and financial comfort are two different conversations.
What This Means for Your Real Estate Business
There was another part of the meeting that I found particularly relevant to Realtors.
Brian explained that his company doesn't expect every Realtor who presents Cash to Win to complete a transaction through the program.
Sometimes the homeowner hears the options and decides to list traditionally.
Sometimes the homeowner obtains a HELOC.
Sometimes the existing property sells before the acquisition program becomes necessary.
The Realtor still helped the homeowner make an informed decision.
That's the part I want you to think about.
You don't need every client to use a specialized financing program for the knowledge to benefit your business.
You need to recognize situations where the traditional transaction structure creates an obstacle.
Think about the opportunities sitting inside your existing database.
You have homeowners who want to downsize but haven't listed. You have move-up buyers waiting for their current property to sell. You have expired listings where the seller's circumstances have changed.
You have homeowners relocating for work.
And you have people who have decided not to move because coordinating two transactions seems overwhelming.
These homeowners don't necessarily need another market update.
They need somebody to help them figure out how to make the move work.
That creates a legitimate reason to reconnect.
Instead of asking whether they're ready to buy or sell, ask what's preventing them from making the move.
Their answer might reveal a problem you and your lending partner can solve.
Start With the Client's Situation, Not the Program
I wouldn't recommend leading every listing presentation with Cash to Win.
And I wouldn't recommend telling every homeowner to get a HELOC.
The program should follow the problem.
If your client has plenty of cash, qualifies comfortably for both mortgages, and doesn't mind carrying two properties, a traditional purchase might be perfectly appropriate.
If they're willing to sell first and move into temporary housing, that might be the most economical approach.
But if they're unwilling to sell before buying, need access to their equity, or have a specific relocation deadline, the conversation changes.
That's when I want you to call me.
We'll review the existing mortgage, available equity, purchase price, cash reserves, and expected selling timeline.
Then we'll compare the available structures.
For any Cash to Win scenario, we'll also need to review the company's actual acquisition terms, daily carrying charges, closing expenses, and resale agreement.
The homeowner should understand the full financial implications before making a decision.
There's no reason to recommend a more expensive structure when a simpler solution accomplishes the same objective.
But there's also no reason to lose a transaction because nobody explored the alternatives.
The Next Time Your Seller Says They Need to Sell First
Before accepting that statement as the end of the conversation, find out what they mean.
Do they need the equity for their down payment?
Do they need to eliminate the existing mortgage payment to qualify?
Are they concerned about carrying two properties?
Or do they simply want the certainty of knowing their current house has sold?
Those are four different problems, and they don't necessarily require the same solution.
For Realtors in Franklin, Brentwood, Spring Hill, Nashville, and the surrounding Middle Tennessee communities, understanding those differences creates an opportunity to help homeowners who otherwise might remain on the sidelines.
I've been in the mortgage business for more than two decades. One lesson I've learned is that the obvious financing solution isn't always the right one.
Sometimes the mortgage is straightforward. The difficult part is figuring out how to coordinate everything around the transaction.
And that's where having an experienced lending partner makes a difference.
If you're working with a homeowner who wants to buy before selling, send me the scenario before assuming they have to wait.
We'll look at the numbers, evaluate the options, and determine what makes sense for your client.
Sources
These links support the regulated, policy, or time-sensitive claims in this alert. Confirm current rules directly with the named source.
- Cash to Win, Seller and Buyer Program Information
Cash to Win describes program options, fees, per-diem charges, and conditions. Actual transaction terms require direct review with the company and the homeowner.
Frequently Asked Questions
Can a homeowner buy a new home before selling the current one?
Sometimes. The workable option depends on equity, cash reserves, qualifying income, the expected sale timeline, and the homeowner's comfort carrying two properties. A sale-first plan, a contingent offer, a HELOC, bridge financing, or an acquisition structure can fit different situations.
How does Cash to Win describe its seller option?
Cash to Win says it can purchase a homeowner's existing property to facilitate proceeds for another purchase. The company describes seller costs and final proceeds as transaction-specific, so the actual agreement, fees, timing, repairs, and resale terms need review before a client decides.
What should a Realtor ask a seller who wants to buy before selling?
Ask whether the seller needs equity for the down payment, needs to eliminate the current mortgage payment, is concerned about carrying two homes, or wants certainty that the current property has sold. Those are different problems and can lead to different solutions.
Is a cash acquisition strategy automatically better than a traditional purchase?
No. A cash strategy can change the offer structure and timing, but the purchase price, financing terms, fees, closing costs, monthly payment, and expected resale outcome still need to be compared together.
What is the difference between mortgage qualification and financial comfort?
Qualification asks whether the borrower meets underwriting requirements. Financial comfort asks whether the homeowner wants to use available cash, maintain reserves, or carry two properties while waiting for a sale. Both questions matter before a move-up purchase.

Keith has helped 2,980+ families close on homes across 12+ markets over 24+ years, with $310M+ in closed loans. He specializes in difficult files, listing-agent partnerships, and the kind of complex deals most lenders turn away.
He writes the Realtor Money Alerts to give agents the plays, programs, and systems that protect deals and generate more closings.
Want plays like this every week?
Drop your email and I'll send you the next one first.
Let's Talk About Your Business
If you want to see if we can get more buyers and sellers for you, a 15-minute call is all it takes. No pitch. No pressure. Just a real conversation about your business.
Keith works with a small number of agents in each market. If there is a fit, you will know by the end of the call.
"Keith helped us get an offer on a $2.8 million dollar listing in Arrington, TN with a custom funnel. Incredible results."
"Keith has been instrumental in the growth of our listing leads coming in. He is a true partner."
We help you grow your business and get you more clients · Keith Goeringer NMLS #488023 · No obligation